Kiffmeister’s #Fintech Daily Digest (20261006)

Eclipsing the Pyramid: Stablecoins and Settlement (JFMI)

The Journal of Financial Market Infrastructures (JFMI) published a paper by Clément Berthou and Xavier Lavayssière that examines stablecoins and the concept of a “settlement eclipse.” The paper shows how stablecoins circulate value globally without requiring traditional fiat redemption, leveraging quasi-bearer claims, programmable platforms, and crypto intermediaries. As a result, stablecoins produce a settlement eclipse, whereby a subordinate layer of the monetary hierarchy internalizes transfers at sufficient scale, and occults the settlement function of layers above it. Such phenomenon obscures systemic risks, transfers financial access control to private operators, and narrows policy options. Analogous occultation occurs when transfer volumes are internalized by large financial institutions, netted within private payment systems, or managed through nested correspondent banking chains. Ultimately, the authors position stablecoins within an emerging “tokenized monetary pyramid,” questioning whether this parallel structure will secure a direct public anchor or remain structurally subordinate to the traditional fiat system. [JFMI]

Project Ensemble Business Use Case Report (HKMA)

The Hong Kong Monetary Authority (HKMA) published a report that details the experiences gained from the first phase of its Project Ensemble that tested end-to-end use cases for settling digital asset transactions using experimental tokenized deposits settled using e-HKD wholesale central bank digital currency (CBDC). Although pilots across fixed income, liquidity management, green finance, and trade finance demonstrated atomic delivery-versus-payment execution, the anticipated efficiency gains face substantial friction. True straight-through processing remains constrained by legacy manual workflows, off-chain data lags, and an unproven critical mass. Furthermore, structural hurdles like potential bank liquidity strains and absent secondary market conventions threaten commercial scalability. In addition, the report acknowledges that policy shifts and regulatory interventions are required to support the viability of such new ecosystems. [HKMA]

BTW if you want to see a complete database of my DFC-related posts going back years, including many that didn’t make the Daily Digest cut, click here.

FYI I produce a monthly digest of digital fiat currency (DFC) developments exclusively for the official sector (e.g., central banks, ministries of finance and international financial institution (e.g., the BIS, IMF, OECD, World Bank)) plus academics and firms that are active in the DFC space (commercial banks, technology providers, consultants, etc.). (DFCs include central bank digital currency (CBDC), stablecoins and tokenized deposits.) It goes out via email on the first business day of every month, and if you’re interested in being on the mailing list, please email me at john@kiffmeister.com.

Kiffmeister’s #Fintech Daily Digest (20261005)

India’s CBDC Moment: From Digital Cash to Programmable Money (S&P)

According to a recent S&P Global report, India’s central bank digital currency (CBDC), the digital rupee, should be judged on programmability and settlement efficiency, not retail wallet adoption. Retail transactions lag significantly behind the ubiquitous Unified Payments Interface (UPI). However, the digital rupee could become a foundational layer of India’s digital public infrastructure by functioning as programmable money for targeted policy outcomes. Furthermore, its most substantial economic promise lies in wholesale markets, where it could facilitate atomic settlement for tokenized assets and reduce cross-border payment friction. And in a potential tokenized global economy, the digital rupee could prevent a shift of cross-border business-to-business trade and remittances toward foreign-currency stablecoins. [S&P]

Digital Pound Lab: Phase 2 Update (BoE)

The Bank of England (BoE) updated its webpage dedicated to Phase 2 of its Digital Pound Lab that concluded in July 2026. BoE-developed use cases demonstrated included one-time aliases for privacy-preserving payments, confirmation of payee, group “kitty” payments using conditional locks, external service interface provider connections enabling third-party app integration, allowances extended to e-commerce, and usage-based streaming micropayments. Eleven private sector participants tested additional use cases that the latest update fleshed out in more detail. These included Crunchfish demonstrating deferred offline payments with a reserve-pay-settle lifecycle and double-spend controls, and TECHT Labs demonstrating conditional business-to-business payments via smart contracts. Interestingly, one of the participants listed in the June 2026 update (Focus on Monesave) was quietly dropped. The BoE explicitly disclaimed policy endorsement of any participant designs, or endorsement of the firms, their products or services. [BoE]

BTW if you want to see a complete database of my DFC-related posts going back years, including many that didn’t make the Daily Digest cut, click here.

FYI I produce a monthly digest of digital fiat currency (DFC) developments exclusively for the official sector (e.g., central banks, ministries of finance and international financial institution (e.g., the BIS, IMF, OECD, World Bank)) plus academics and firms that are active in the DFC space (commercial banks, technology providers, consultants, etc.). (DFCs include central bank digital currency (CBDC), stablecoins and tokenized deposits.) It goes out via email on the first business day of every month, and if you’re interested in being on the mailing list, please email me at john@kiffmeister.com.

Kiffmeister’s #Fintech Daily Digest (20261004)

The Russian Ministry of Finance Paying Wages in Digital Rubles (Russian MOF)

Russia’s Ministry of Finance (MOF) reports that, on October 1, 2026, several employees opted to receive salary payments in digital rubles through wallets on the Bank of Russia platform. It follows pilot federal-budget transactions in 2025, covering salaries, stipends and selected government-contract payments, with aggregate volume of nearly 16 million rubles. Since January 2026, federal institutions have been permitted to make and receive budget-related payments in digital rubles without a restricted expenditure list. The initiative therefore marks a shift from controlled pilot use toward routine Treasury and payroll integration, contingent on bank and merchant infrastructure that opened up on September 1, 2026. [Russian MOF]

Will US Firms Adopt Stablecoins? Survey Says They’re Not Enthusiastic (Cleveland Fed)

In a U.S. Federal Reserve Bank of Cleveland Economic Commentary, Dirtzu, Panzitta and Zimmerman surveyed 148 firms in the Fourth District (Ohio, western Pennsylvania, eastern Kentucky, and northern West Virginia) regarding plans to use stablecoins. Despite the 2025 Guiding and Establishing National Innovation for U.S. Stablecoins (GENIUS) Act easing supply constraints, they find negligible latent corporate demand. Only one firm currently uses stablecoins, while seven plan future adoption. Primary deterrents include satisfaction with existing payment rails, knowledge gaps, and absent counterparty demand. While analysis of Securities and Exchange Commission (SEC) nonfinancial corporate balance sheet filings seemingly corroborates this disinterest, the authors dismiss stablecoin holdings below a 2% total asset threshold as trivial, which risks obscuring early-stage corporate experimentation. [Cleveland Fed]

UK Banks Complete First Live Customer Transactions Using tokenized Sterling Deposits (UK Finance)

[September 24, 2026] Seven U.K. banks collaborated to complete the first live customer transactions using tokenized sterling deposits on a shared platform developed by Quant, delivered through the Great British Tokenised Deposit (GBTD) initiative convened by UK Finance. The participating banks (Barclays, HSBC UK, Lloyds, Monzo, Nationwide, NatWest and Santander) tested conditional payments in two remortgage completions and a consumer marketplace exchange, in which customer balances were locked and automatically released when specified completion or delivery conditions were met. The pilots seek to preserve the legal and prudential characteristics of bank deposits while adding programmable, interoperable settlement functionality. Planned work includes tokenized bank-issued debt instruments and digital-asset settlement using delivery-versus-payment-versus-reserves. The announcement demonstrates operational feasibility, rather than resolving questions of scale, governance, interoperability, legal finality, or supervisory treatment. [UK Finance]

International Stablecoin Flows, Capital Controls and Currency Crises (IMF)

The IMF published a working paper by Marco Reuter that analyzes $21.4 trillion in international stablecoin flows across 188 countries from 2018 to 2025. These US dollar-pegged assets are concentrated in emerging markets and developing economies, which hold 75% of the total. Flows are predominantly cross-border, retail-sized transfers with a median size of $300. Furthermore, when countries restrict capital outflows, stablecoin activity rises persistently by roughly 30% over six months. Similarly, currency crises trigger a persistent 75% increase in holdings within a year. However, country-level geography is inferred via machine learning trained on domain-name linguistics and web traffic—proxies vulnerable to virtual private network (VPN) distortions, unrepresentative sampling, and the untestable assumption of equal average transaction sizes across countries. [IMF]

Tokenization of Real World Assets: Towards Embedded Crypto Finance (DC Fintech Week)

A paper by Zetzsche, Buckley and Arner that focuses on tokenization of non-financial real-world assets (TRWAs) develops a tokenization taxonomy to better understand what TRWAs entail. The authors contend that TRWAs could transform mainstream custody and securitization through continuous 24/7 settlement and central bank digital currency (CBDC) interoperability, forecasting a gradual shift toward “embedded crypto finance.” To govern this transition, they propose adapting existing securitization rules, such as expanding substituted compliance for prospectuses. This approach relies heavily on legacy frameworks to manage the unique operational and cyber risks of distributed ledger technologies, leaving open the question of whether unprecedented on-chain vulnerabilities might ultimately fall through the regulatory cracks. [DC Fintech Week]

The Compatibility of Permissionless Networks and Financial Integrity (DC Fintech Week)

A paper by Rettig, Malekan and Mosier posits that regulated financial institutions can build and use permissionless networks in compliance with financial integrity obligations. While some see the pseudonymous, decentralized nature of these networks as insurmountable compliance barriers, the authors contend that compliance can be achieved by implementing risk-based controls strictly at the application layer, rather than attempting to police the underlying neutral network protocol. Ultimately, they frame embracing open protocols not merely as a manageable risk, but as a strategic imperative, to unlock superior operational resilience and market efficiency compared to permissioned alternatives. Whether regulatory authorities will embrace this neat bifurcation of network carriage and application liability in practice remains to be seen. [DC Fintech Week]

BTW if you want to see a complete database of my DFC-related posts going back years, including many that didn’t make the Daily Digest cut, click here.

FYI I produce a monthly digest of digital fiat currency (DFC) developments exclusively for the official sector (e.g., central banks, ministries of finance and international financial institution (e.g., the BIS, IMF, OECD, World Bank)) plus academics and firms that are active in the DFC space (commercial banks, technology providers, consultants, etc.). (DFCs include central bank digital currency (CBDC), stablecoins and tokenized deposits.) It goes out via email on the first business day of every month, and if you’re interested in being on the mailing list, please email me at john@kiffmeister.com.

Kiffmeister’s #Fintech Daily Digest (20261002)

The Open Standard OUSD U.S. Dollar Stablecoin in Now Live (Open Standard)

[September 30, 2026] Open Standard launched its Open USD (OUSD) U.S. dollar-pegged stablecoin. The founding five (Coinbase, Mastercard, Shopify, Stripe, and Visa) have reportedly committed to minting $1 billion worth of OUSD to seed initial liquidity, and each received an equal initial equity stake. OUSD is issued by Bridge, a Stripe company, and runs natively on Base, Ethereum, Solana, and Tempo, with reserves held at BlackRock, Lead Bank and BNY. Reserve attestations will be published monthly at reserves.bridge.xyz/ousd. Businesses can mint and redeem OUSD 1:1 against the dollar through BVNK, Stripe, and the Visa Stablecoin Platform. [Open Standard]

How Central Banks Can Win the Digital Currency Race (CSIS)

The Center for Strategic and International Studies (CSIS) published a paper by Luck, Gray and Hu arguing central banks treat adoption, sovereignty, and security as independent variables, generating secure but underutilized retail central bank digital currencies (CBDCs). Evaluating failed pilots against successful fast-payment systems (FPSs), the report suggests mass adoption requires sub-incumbent pricing and permissive nonbank access built upon a central bank-managed settlement layer, as seen with Brazil’s Pix and India’s UPI. However, advanced economy central banks are systemically constrained from providing this utility by the risk of disintermediating commercial banks. But rather than resolving this retail CBDC design trilemma, the authors pivot to advocating for central bank-coordinated FPSs, leaving the question of how to design a successful retail CBDC unanswered. [CSIS]

BTW if you want to see a complete database of my DFC-related posts going back years, including many that didn’t make the Daily Digest cut, click here.

FYI I produce a monthly digest of digital fiat currency (DFC) developments exclusively for the official sector (e.g., central banks, ministries of finance and international financial institution (e.g., the BIS, IMF, OECD, World Bank)) plus academics and firms that are active in the DFC space (commercial banks, technology providers, consultants, etc.). (DFCs include central bank digital currency (CBDC), stablecoins and tokenized deposits.) It goes out via email on the first business day of every month, and if you’re interested in being on the mailing list, please email me at john@kiffmeister.com.

Kiffmeister’s #Fintech Daily Digest (20260929)

Call for Expressions of Interest to Explore Digital Euro Innovation Platform Activities (ECB)

The European Central Bank (ECB) launched a call for expressions of interest inviting private companies and organizations to collaborate in exploring how the digital euro can foster innovation in the market via two workstreams. The experimentation workstream will explore electronic integrated receipts, multi-payer and conditional payments, and payment-app features. The exploration work stream will explore artificial intelligence in payments and public-sector uses. The work could inform services built on the digital euro’s core infrastructure and possible future design changes. Applications close November 9, 2026, with activities planned for the first half of 2027. [ECB]

Trusted Execution Environments for Central Banks (BIS)

The Bank for International Settlements (BIS) published a paper that considers what trusted execution environments (TEEs) can responsibly deliver for central banks, the conditions under which they are most effective and how they can be deployed without widening who must be trusted. A TEE is a hardware-anchored, isolated computing space protecting “data in use” via verifiable code authenticity and runtime confidentiality. This capability is critical, enabling institutions to collaboratively analyze sensitive microdata without exposing raw records to peers or infrastructure operators. Yet, significant unresolved vulnerabilities persist, specifically regarding microarchitectural side-channel leakage, host-mediated subversion, and attestation failures. Consequently, TEEs offer conditional assurances rather than absolute security, demanding rigorous, evidence-based governance and layered mitigations to be viable. [BIS]

And some backfilling:

E-Cedi Project Still Active — BoG Governor Assures (BOG)

[May 20, 2026] Bank of Ghana (BOG) Dr. Johnson Asiama assured that the e-cedi project has not been abandoned, despite delays in its rollout, speaking at the 130th Monetary Policy Committee meeting. He explained that the central bank is taking additional time to complete key preparatory stages before fully deploying the initiative. The Bank is prioritizing critical systems and safeguards, particularly cybersecurity resilience, before moving to the next phase of implementation. [BOG]

BTW if you want to see a complete database of my DFC-related posts going back years, including many that didn’t make the Daily Digest cut, click here.

FYI I produce a monthly digest of digital fiat currency (DFC) developments exclusively for the official sector (e.g., central banks, ministries of finance and international financial institution (e.g., the BIS, IMF, OECD, World Bank)) plus academics and firms that are active in the DFC space (commercial banks, technology providers, consultants, etc.). (DFCs include central bank digital currency (CBDC), stablecoins and tokenized deposits.) It goes out via email on the first business day of every month, and if you’re interested in being on the mailing list, please email me at john@kiffmeister.com.

Kiffmeister’s #Fintech Daily Digest (20260928)

Remunerating Means of Payment (Bruegel)

Bruegel published a paper by Ulrich Bindseil that concludes that regulatory constraints on remunerating electronic means of payments are either ineffective or undermine financial stability and efficiency. No economic theory of the interest-rate spread between money and adjacent financial assets implies that means of payment must be unremunerated. Furthermore, enforcing non-remuneration acts as a regressive tax proportional to nominal interest rates, transferring wealth from users to issuers. Such constraints are easily circumvented, generating financial flows that could threaten market stability. Although some defend these restrictions as necessary to protect bank deposit franchises and systemic stability, the paper finds such claims insufficiently founded, serving only as temporary measures when superior regulatory tools are absent. Consequently, tiered remuneration for digital currencies should be adopted. [Bruegel]

BTW if you want to see a complete database of my DFC-related posts going back years, including many that didn’t make the Daily Digest cut, click here.

FYI I produce a monthly digest of digital fiat currency (DFC) developments exclusively for the official sector (e.g., central banks, ministries of finance and international financial institution (e.g., the BIS, IMF, OECD, World Bank)) plus academics and firms that are active in the DFC space (commercial banks, technology providers, consultants, etc.). (DFCs include central bank digital currency (CBDC), stablecoins and tokenized deposits.) It goes out via email on the first business day of every month, and if you’re interested in being on the mailing list, please email me at john@kiffmeister.com.

Kiffmeister’s #Fintech Daily Digest (20260927)

Just for the record, I’ve sharpened my description of the People’s Bank of China (PBOC) e-CNY pivot from a central bank digital currency (CBDC) to a tokenized commercial bank deposit platform:

e-CNY 2.0 Pivot from Central Bank Digital Currency to Tokenized Deposits (PBOC)

On December 29, 2025, the People’s Bank of China (PBOC) announced the digital yuan (e-CNY) transition from central bank digital currency to a tokenized commercial bank interest-paying deposit platform. The PBOC also introduced a “global single ledger” (GSL) that operates like a centralized real-time gross settlement system. The GSL binds payment instructions and settlement together to eliminate correspondent clearing delays. The PBOC embeds regulatory nodes into the network to have real-time, comprehensive visibility of all interbank flows for risk management and financial integrity purposes. And to reduce settlement latency, settlement on the GSL is separated from the execution of smart contracts (metadata enabling automated transaction execution based on predefined rules). Smart contract execution is offloaded to parallel, permissioned blockchain networks where programmability acts as a temporary conditional lock. Once conditions are met, the programming is stripped away, and the funds settle across the GSL to the receiving bank as unrestricted money. Only earmarked funds held in sub-wallets retain post-transfer restrictions set by “parent” wallets. [PBOC]

How Pontes (DLT) Reinvented the Time-Out and Got it Wrong (LinkedIn)

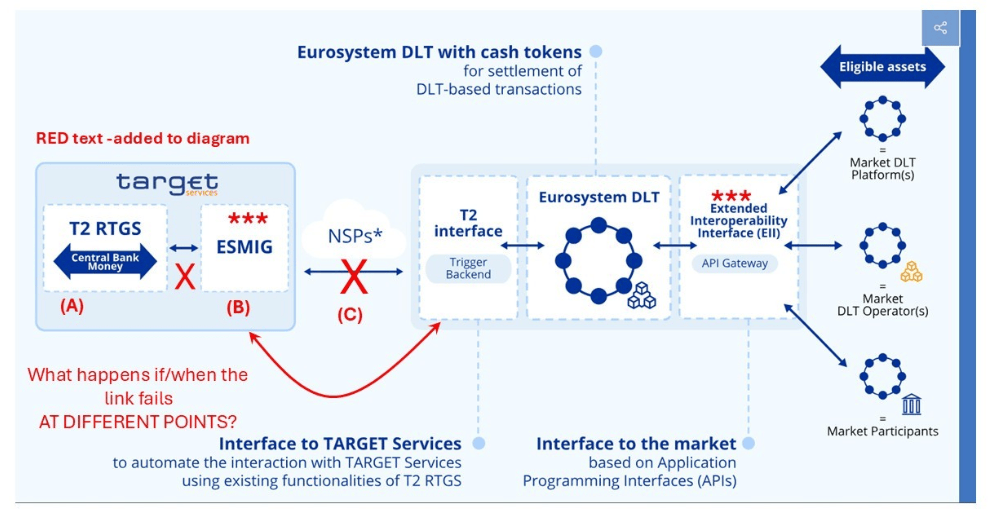
Patrick McConnell, in a September 22 LinkedIn post, argued that the European Central Bank Pontes tokenized asset settlement system pilot utilizes a flawed hash-link protocol (HLP). Pontes employs a dual settlement model, one of which settles cash legs directly in the Eurosystem’s T2 real-time gross settlement system via application programming interface triggers to achieve central bank money settlement finality. Patrick claims the HLP implements time-outs without unique transaction sequence numbers or duplicate identification flags. Consequently, delayed but successful transactions could be erroneously marked unsettled, creating double-payment risks upon resubmission. This vulnerability renders the Eurosystem Single Market Infrastructure Gateway a single point of failure with unpredictable outcomes, violating the Digital Operational Resilience Act. Comments posit that T2’s underlying reconciliation layer reduces the double-payment risk to a “tie-out problem” rather than lost funds, and that the architecture is fundamentally flawed for locking payments before verifying asset availability. [LinkedIn]

BTW if you want to see a complete database of my DFC-related posts going back years, including many that didn’t make the Daily Digest cut, click here.

FYI I produce a monthly digest of digital fiat currency (DFC) developments exclusively for the official sector (e.g., central banks, ministries of finance and international financial institution (e.g., the BIS, IMF, OECD, World Bank)) plus academics and firms that are active in the DFC space (commercial banks, technology providers, consultants, etc.). (DFCs include central bank digital currency (CBDC), stablecoins and tokenized deposits.) It goes out via email on the first business day of every month, and if you’re interested in being on the mailing list, please email me at john@kiffmeister.com.

Kiffmeister’s #Fintech Daily Digest (20260925)

HKMA to Introduce Wholesale CBDC as Project EnsembleTX Settlement Asset (HKMA)

The Hong Kong Monetary Authority (HKMA) is planning to make a wholesale central bank digital currency (CBDC) available for interbank settlement of tokenized deposits as part of Project EnsembleTX, enabling 24/7 payments by around the end of 2026, and will continue to explore more use cases for tokenized deposits. The pilot, launched in November 2025, initially used the HKD real-time gross settlement (RTGS) system to settle the transactions. [HKMA]

ECB Assessing Feasibility of Interlinking TIPS with Brazil’s Pix (ECB)

The European Central Bank (ECB) will assess the feasibility of linking the Eurosystem’s TARGET Instant Payment Settlement (TIPS) platform to Central Bank of Brazil’s Pix instant-payment system. A link could make payments between the euro area and Brazil faster and cheaper, extending the Eurosystem’s broader effort to connect TIPS with foreign instant-payment systems. However, technical, operational, legal and business arrangements remain to be evaluated. [ECB]

US FRB Proposes Rules for FRB-Regulated Stablecoin Issuers (FRB)

The U.S. Federal Reserve Board (FRB) proposed two rules to implement the Guiding and Establishing National Innovation for U.S. Stablecoins (GENIUS) Act for FRB-supervised payment stablecoin issuers: one governing issuance, reserves and supervision, and another governing applications by supervised banks. The first would require full backing with eligible liquid assets, including short-term Treasury bills, and set capital and risk-management standards; it would also regulate reserve-asset safekeeping and clarify permissible bank activities. The second would require applicants to provide a business plan and financial information and establish procedures for appeals and final decisions. Their final terms remain subject to comment, due 60 days after Federal Register publication. [FRB]

BTW if you want to see a complete database of my DFC-related posts going back years, including many that didn’t make the Daily Digest cut, click here.

FYI I produce a monthly digest of digital fiat currency (DFC) developments exclusively for the official sector (e.g., central banks, ministries of finance and international financial institution (e.g., the BIS, IMF, OECD, World Bank)) plus academics and firms that are active in the DFC space (commercial banks, technology providers, consultants, etc.). (DFCs include central bank digital currency (CBDC), stablecoins and tokenized deposits.) It goes out via email on the first business day of every month, and if you’re interested in being on the mailing list, please email me at john@kiffmeister.com.
Kiffmeister’s #Fintech Daily Digest (20260924)

Central Bank of Uzbekistan Exploring Wholesale CBDC (CBU)

[August 30, 2026] At the inaugural Silk Road Finance and Technology Forum (SRFTF), Central Bank of Uzbekistan (CBU) officials outlined a model under consideration in which a wholesale central bank digital currency (CBDC) could provide a trusted settlement layer for privately issued stablecoins, with licensed institutions managing customer relationships and initial testing taking place through a regulatory sandbox. The SRFTF was co-organized by the CBU and the Global Finance & Technology Network (GFTN). The CBU has since posted on its website a white paper co-authored by the GFTN and the Official Monetary and Financial Institutions Forum (OMFIF) that explores the advantages and disadvantages of wholesale CBDCs in the Uzbekistan context. The report assesses if wholesale CBDC could securely improve domestic capital markets and cross-border settlements. However, it critically questions whether alternative synchronization systems might achieve these goals more cost-effectively, proposing a rigorous 24-month evaluative roadmap. [CBU]

Six Canadian Banks Explore Development of a Secure CAD Tokenized Deposit Solution (CIBC)

Six Canadian banks are jointly exploring the development of Canadian dollar based digital money solutions, starting with a tokenized deposits initiative. The project seeks to deliver faster, more efficient and programmable payments to Canadian customers while preserving safety, stability, and effective regulatory oversight. The first phase aims to move tokenized deposits efficiently across Canadian financial institutions with a longer term goal to connect with other emerging digital assets initiatives. The participants are Bank of Montreal (BMO), Canadian Imperial Bank of Commerce (CIBC), National Bank of Canada (NBC), Royal Bank of Canada (RBC), The Bank of Nova Scotia (Scotiabank), and TD Bank Group (TD). The participants anticipate the inclusion of other deposit-taking institutions at the appropriate time. [CIBC]